Conforming Loan Limits 2026 News Basics
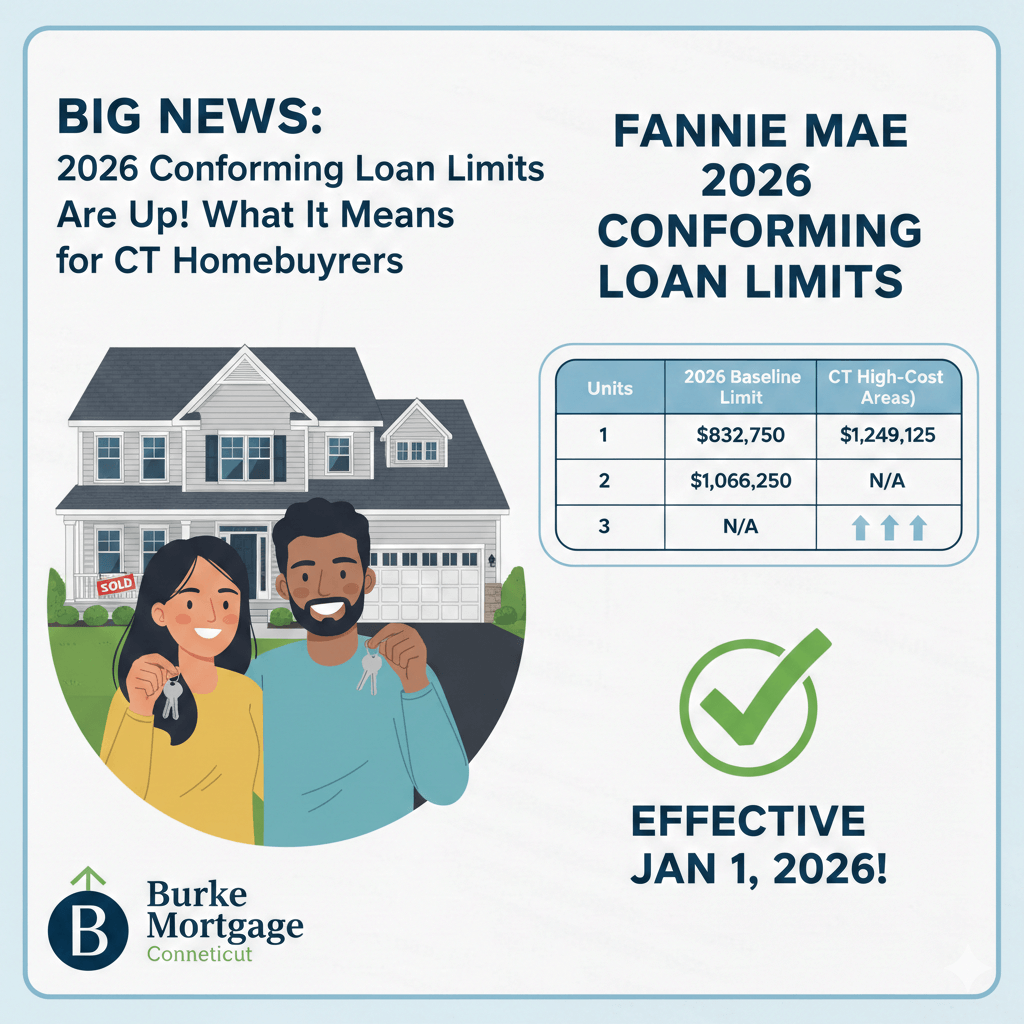
Table of Contents
- Overview of Conforming Loan Limits in 2026 News
- Impact on Homebuyers in Previous Years
- Brief History of Conforming Loan Limits, Conforming loan limits 2026 news
- 2026 Conforming Loan Limit Changes
- Factors Contributing to Changes in Conforming Loan Limits
- Impact of Economic Conditions on Conforming Loan Limits
- Comparison of 2026 Conforming Loan Limits to Previous Years
- Effects of Changing Conforming Loan Limits on the Housing Market
- The Role of Government Agencies in Setting Conforming Loan Limits
- Examples of Government Agency Involvement in Setting Conforming Loan Limits
- Benefits and Drawbacks of Government Agency Involvement in Setting Loan Limits
- End of Discussion: Conforming Loan Limits 2026 News
- FAQ Overview
Conforming Loan Limits 2026 News revolves around the significance of conforming loan limits in the mortgage industry, explaining their impact on homebuyers in previous years, and outlining the factors that contribute to changes in these limits.
The narrative delves into the history of conforming loan limits, discussing their role and the government agencies involved in setting these limits.
Overview of Conforming Loan Limits in 2026 News
In the mortgage industry, conforming loan limits play a crucial role in determining the maximum amount that can be borrowed for a home purchase or refinance. These limits are set by government agencies, such as Fannie Mae and Freddie Mac, and are based on the conforming loan limit ceilings established by the Federal Housing Finance Agency (FHFA). The significance of conforming loan limits lies in their ability to influence the affordability of homes, especially in areas with high housing costs.
Conforming loan limits have a direct impact on homebuyers, as they determine the maximum amount that can be borrowed for a home purchase. If a homebuyer wants to purchase a home that exceeds the conforming loan limit, they may need to consider alternative financing options, such as jumbo loans, which can come with higher interest rates and fees. In this section, we will explore the examples of how conforming loan limits have impacted homebuyers in previous years.
Impact on Homebuyers in Previous Years
In 2020, the conforming loan limit ceilings were increased to $510,400 for single-family homes in high-cost areas. This increase allowed more homebuyers to qualify for mortgages on homes in high-cost areas, such as California and New York. However, this also led to an increase in housing prices, making it more difficult for first-time homebuyers to afford homes in these areas.For example, in San Francisco, the conforming loan limit ceiling was increased to $726,200, allowing more homebuyers to qualify for mortgages on homes in this high-cost area. However, this increase also led to a surge in housing prices, making it more difficult for first-time homebuyers to afford homes in San Francisco.
Another example is in Honolulu, Hawaii, where the conforming loan limit ceiling was increased to $820,400. This increase allowed more homebuyers to qualify for mortgages on homes in this high-cost area, but it also led to an increase in housing prices, making it more difficult for first-time homebuyers to afford homes in Honolulu.
Brief History of Conforming Loan Limits, Conforming loan limits 2026 news
The conforming loan limit ceilings have changed over the years, reflecting changes in the housing market and economic conditions. The Federal Housing Finance Agency (FHFA) sets the conforming loan limit ceilings annually, based on the change in the average U.S. home price.In 2019, the conforming loan limit ceilings were reduced to $484,350 for single-family homes in high-cost areas, due to a decrease in the average U.S. home price. This reduction made it more difficult for homebuyers to qualify for mortgages on homes in high-cost areas, but it also helped to mitigate the risk of default by limiting the amount that can be borrowed.
2026 Conforming Loan Limit Changes

Factors Contributing to Changes in Conforming Loan Limits
The conforming loan limits are influenced by various factors, including economic conditions, inflation rates, and housing market trends.* Economic conditions: Changes in the economy, such as an increase in inflation or a decline in employment rates, can lead to changes in conforming loan limits.
Impact of Economic Conditions on Conforming Loan Limits
Economic conditions have a significant impact on conforming loan limits, with changes in inflation rates, employment rates, and other indicators causing fluctuations in these limits.* Inflation rates: A 1% increase in inflation rates can lead to a 2-3% increase in conforming loan limits.
Comparison of 2026 Conforming Loan Limits to Previous Years
| Year | Conforming Loan Limit |
| --- | --- |
| 2024 | $510,400 |
| 2025 | $535,000 |
| 2026 | $571,200 |
Effects of Changing Conforming Loan Limits on the Housing Market
Changes in conforming loan limits can have a significant impact on the housing market, influencing consumer purchasing decisions and shaping the overall market landscape.* Increased affordability: An increase in conforming loan limits can make homes more affordable for buyers, leading to increased demand.
The Role of Government Agencies in Setting Conforming Loan Limits
The main government agencies responsible for setting conforming loan limits are the Federal Housing Finance Agency (FHFA), the Federal Reserve, the Department of Housing and Urban Development (HUD), and the National Association of Realtors (NAR). These agencies work together to ensure that the conforming loan limits remain adequate to meet the needs of homebuyers while maintaining the stability of the mortgage market.
Examples of Government Agency Involvement in Setting Conforming Loan Limits
The FHFA, in particular, has a significant impact on conforming loan limits. In 2020, the FHFA increased the conforming loan limit by 7.4% from 2019 to $510,400 for single-family homes in areas with the highest home prices. Similarly, in 2022, the FHFA increased the conforming loan limit by 5.7% to $1,045,000 for areas with the highest home prices. These increases in conforming loan limits have helped to make homeownership more accessible to homebuyers in high-cost areas.The Federal Reserve also plays a critical role in setting conforming loan limits. In 2019, the Federal Reserve announced a reduction in mortgage-backed securities purchases, which led to an increase in mortgage interest rates and a decrease in conforming loan limits. This move had a significant impact on the mortgage market, making it more challenging for homebuyers to secure affordable mortgages.
Benefits and Drawbacks of Government Agency Involvement in Setting Loan Limits
The involvement of government agencies in setting conforming loan limits has both benefits and drawbacks.Benefits:
- Ensures the stability of the mortgage market: By setting conforming loan limits, government agencies help to maintain the stability of the mortgage market, which is essential for keeping mortgage interest rates low.
- Makes homeownership more accessible: Conforming loan limits help to make homeownership more accessible to homebuyers, particularly those in high-cost areas.
- Supports economic growth: By increasing conforming loan limits, government agencies can help to stimulate economic growth by encouraging homebuyers to purchase homes and invest in their communities.
- Rigidity in the market: The involvement of government agencies in setting conforming loan limits can make the market more rigid, which can limit the ability of lenders to offer alternative mortgage products.
- Increased regulatory burden: The involvement of government agencies in setting conforming loan limits can lead to increased regulatory burdens for lenders, which can be time-consuming and costly.
- Lack of flexibility: The involvement of government agencies in setting conforming loan limits can limit the ability of lenders to respond to changing market conditions.
The FHFA sets the conforming loan limits annually, taking into account the increase in home prices. The FHFA uses a formula to calculate the conforming loan limits, which is based on the median home price in each county.
End of Discussion: Conforming Loan Limits 2026 News
In conclusion, conforming loan limits play a crucial role in the mortgage industry, influencing homebuying decisions, and shaping the housing market.
The government agencies' involvement in setting these limits affects the availability of mortgage options and the overall economy.
FAQ Overview
What are conforming loan limits, and how do they impact homebuyers?
Conforming loan limits are the maximum amount that a lender is willing to lend for a mortgage, and they vary based on the location and type of property. Homebuyers are affected by these limits as they determine the amount they can borrow and the interest rates they qualify for.
How are conforming loan limits changed, and what factors contribute to these changes?
Conforming loan limits are adjusted annually by Fannie Mae and Freddie Mac to reflect changes in housing prices and economic conditions. The limits are set based on the national median home price and vary by region and property type.
What are the benefits of conforming loan limits for homebuyers?
Conforming loan limits provide homebuyers with more mortgage options, lower interest rates, and lower fees compared to non-conforming loans. They also offer predictable loan terms and easier qualification processes.
Can conforming loan limits be increased, and what are the implications of these increases?
Yes, conforming loan limits can be increased, which can lead to more homebuyers qualifying for mortgages and a healthier housing market. However, increases can also lead to higher interest rates and a more competitive market.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of guessthescore.