Determine Your Property Tax Obligations
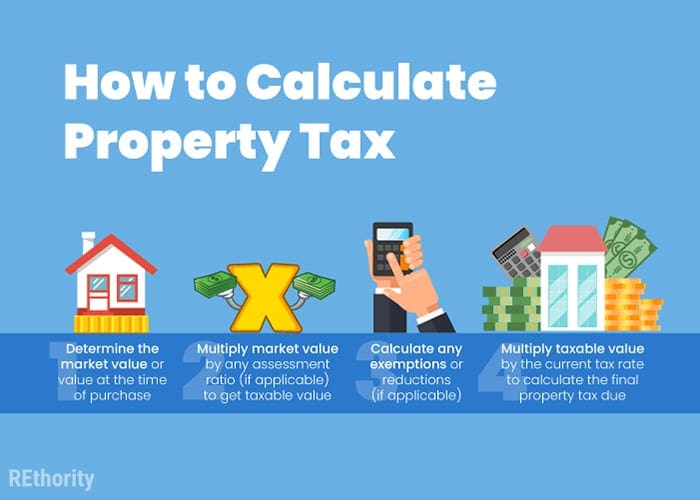
Table of Contents
- Understanding Property Tax Laws and Regulations
- Differences Between State, County, and Local Property Tax Laws
- State Property Tax Laws
- County Property Tax Laws
- Local Property Tax Laws
- Calculating Property Tax Assessments
- The Cost Approach
- The Income Approach
- Comparing the Cost Approach and the Income Approach
- Determining Property Tax Rates and Levies
- Local Funding Needs
- Available Resources
- Calculating Property Tax Rates and Levies
- Identifying Exemptions and Deductions
- Types of Property Tax Exemptions
- Homestead Exemption
- Senior Exemption
- Disability Exemption
- Types of Property Tax Deductions
- Portion Deduction
- Special Assessment Deduction
- How Exemptions and Deductions are Applied, How to calculate property tax
- Considering Special Assessments and Levies
- Types of Special Assessments
- Calculating Special Assessments
- Paying Special Assessments
- Organizing Property Tax Payments and Records
- Why Accurate Records are Essential
- Tips for Organizing Property Tax Payments and Records
- Tracking Property Tax Payments
- Understanding Property Tax Liens and Foreclosure
- Creation and Enforcement of Property Tax Liens
- Tax Foreclosure: A Last Resort for Governments
- Impact on Property Owners: Consequences of Tax Foreclosure
- Calculating Property Tax Savings with Improvements
- Understanding the Impact of Improvements on Property Value
- Calculating Potential Property Tax Savings
- Benefits of Energy-Efficient Improvements
- Timing and Documentation
- Designing a Property Tax Budget and Plan
- Identifying Property Tax Obligations
- Estimating Property Value Adjustments
- Calculating Projected Property Tax Savings
- Reviewing and Adjusting the Property Tax Budget
- Summary
- FAQ Section: How To Calculate Property Tax
How to calculate property tax is a crucial step in understanding your property tax obligations and ensuring compliance with property tax laws. The process of calculating property tax involves understanding property tax laws and regulations, calculating property tax assessments, determining property tax rates and levies, identifying exemptions and deductions, considering special assessments and levies, organizing property tax payments and records, understanding property tax liens and foreclosure, and calculating property tax savings with improvements.
The complexity of property tax laws and regulations can be overwhelming, especially for first-time property owners. However, by understanding the importance of property tax laws and regulations, property owners can determine their property tax obligations and make informed decisions about their property tax payments.
Understanding Property Tax Laws and Regulations
Property tax laws and regulations play a crucial role in determining property tax rates and obligations for property owners. These laws and regulations are enacted at various levels of government, including state, county, and local levels, which can lead to differences in the way property taxes are assessed and collected.
Differences Between State, County, and Local Property Tax Laws
The key differences between state, county, and local property tax laws lie in their scope, authority, and application. Each of these levels of government has its own set of laws and regulations that govern property taxes, which can result in unique aspects such as tax rates, exemptions, and assessment procedures. Understanding these differences is essential for property owners to comprehend their tax obligations.
State Property Tax Laws
State property tax laws provide the framework for property taxation at the state level. These laws typically Artikel the tax rates, assessment methods, and exemptions that apply to properties within the state. State laws may also provide funding for various public services and programs, such as education, public safety, and infrastructure.
- Property Tax Rates: State laws often establish a range of tax rates that apply to different types of properties, such as residential or commercial.
- Assessment Methods: States may use different methods to assess property values, including property value assessments or income approaches.
- Exemptions: State laws may provide exemptions for certain types of properties, such as owner-occupied homes or non-profit organizations.
- Funding for Public Services: State laws may allocate revenue from property taxes to fund various public services and programs.
County Property Tax Laws
County property tax laws govern the assessment and collection of property taxes at the county level. These laws typically provide more detailed guidance on the tax rates, assessment methods, and exemptions that apply to properties within the county. County laws may also authorize the creation of special taxing districts, such as school districts or fire districts.
- Property Tax Rates: County laws often establish tax rates that apply to specific types of properties, such as residential or commercial.
- Special Taxing Districts: County laws may authorize the creation of special taxing districts to fund specific services or programs.
- Assessment Methods: County laws may use different methods to assess property values, including property value assessments or income approaches.
- Funding for Public Services: County laws may allocate revenue from property taxes to fund various public services and programs.
Local Property Tax Laws
Local property tax laws govern the assessment and collection of property taxes at the municipal or city level. These laws typically provide the most detailed guidance on the tax rates, assessment methods, and exemptions that apply to specific properties within the local area. Local laws may also authorize the creation of special taxing districts or assessment procedures.
- Property Tax Rates: Local laws often establish tax rates that apply to specific types of properties, such as residential or commercial.
- Special Taxing Districts: Local laws may authorize the creation of special taxing districts to fund specific services or programs.
- Assessment Methods: Local laws may use different methods to assess property values, including property value assessments or income approaches.
- Funding for Public Services: Local laws may allocate revenue from property taxes to fund various public services and programs.
Property tax laws and regulations can be complex and may evolve over time, it is essential for property owners to stay informed about the laws and regulations that apply to their properties.
Calculating Property Tax Assessments
Calculating property tax assessments is a crucial step in determining the amount of property taxes that an individual or organization owes to the government. This process involves using current market values and tax rates to arrive at a fair and accurate assessment.
When calculating property tax assessments, two primary methods are used: the cost approach and the income approach.
The Cost Approach
The cost approach involves estimating the replacement cost of a property, which is the cost of reconstructing the property from scratch using current market prices. This approach is based on the idea that a property's value equals the cost of constructing an equivalent property.- Determine the land value: Estimate the value of the land component of the property, which includes the value of the land itself and any improvements that are made to it.
- Estimate the value of improvements: Determine the value of the improvements made to the land, such as buildings, fixtures, and equipment.
- Calculate the total value: Add the land value and the improvements value to determine the total value of the property.
The Income Approach
The income approach involves estimating the value of a property based on its income-generating potential. This approach is based on the idea that a property's value equals its income-generating capacity.The income approach is often used for income-producing properties, such as rental apartments or commercial buildings.
- Determine the net operating income (NOI): Calculate the NOI by subtracting operating expenses from gross income.
- Estimate the capitalization rate: Determine the capitalization rate, which is a percentage that represents the return on investment for a property.
- Calculate the value: Divide the NOI by the capitalization rate to determine the value of the property.
Comparing the Cost Approach and the Income Approach
Both the cost approach and the income approach are widely used for calculating property tax assessments. The choice between the two approaches depends on the type of property, its characteristics, and its income-generating potential.When using the cost approach, it is essential to consider factors such as replacement costs, zoning regulations, and market conditions. When using the income approach, it is crucial to consider factors such as operating expenses, income-generating potential, and market conditions.
Both approaches require careful consideration of relevant factors and accurate data to ensure an accurate and fair property tax assessment.
Determining Property Tax Rates and Levies
Property tax rates and levies are essential components of the taxation system, influencing the amount of money collected from property owners. These rates and levies are typically set by local governments to fund public services and infrastructure. The amount collected is based on various factors, including the value of the property, local funding needs, and available resources.Local Funding Needs
Local funding needs play a significant role in determining property tax rates and levies. Governments use the revenue generated from property taxes to fund essential services such as:- Maintenance of public roads and highways
- Public education and transportation
- Fire and police services
- Social services and welfare programs
Available Resources
The available resources, such as the economy, employment rates, and property values, also influence property tax rates and levies. For instance:- An increase in property values can result in increased property tax revenue, allowing for lower rates or increased spending on public services.
- A decline in property values can lead to reduced property tax revenue, necessitating higher tax rates or reduced spending on public services.
- An improvement in the local economy can lead to increased property tax revenue, enabling local governments to reduce tax rates or invest in new Public-Private Partnerships.
Calculating Property Tax Rates and Levies
The calculation of property tax rates and levies typically involves a formula-based approach, considering various factors such as:- The assessed value of the property
- The tax rate or levy applied to the assessed value
- Any applicable exemptions or deductions
Property Tax = Assessed Value x Tax RateAssuming a property tax rate of 1.5% and an assessed value of $200,000, the property tax would be:
$200,000 x 1.5% = $3,000
The tax rate and levy are typically adjusted over time to reflect changes in local funding needs, available resources, and economic conditions. This ensures that property tax rates remain reasonable and do not disproportionately burden property owners.
Identifying Exemptions and Deductions
Property tax exemptions and deductions are crucial factors that can significantly reduce the tax liability for property owners. These exemptions and deductions can vary depending on the location, type of property, and individual circumstances. Understanding the different types of exemptions and deductions available can help property owners save money on their property taxes.Types of Property Tax Exemptions
There are several types of property tax exemptions available to property owners, each with its own set of eligibility criteria and benefits.*
Homestead Exemption
The homestead exemption is one of the most common types of property tax exemptions. This exemption is available to property owners who occupy their primary residence and have a certain level of income or ownership interest in the property. The homestead exemption can reduce the taxable value of the property by a specific percentage, which varies depending on the location and individual circumstances.Senior Exemption
Disability Exemption
Types of Property Tax Deductions
In addition to exemptions, property owners can also claim deductions on their property taxes. These deductions can reduce the total amount of property taxes owed.*
Portion Deduction
The portion deduction is available to property owners who have multiple properties and can only occupy one of them as their primary residence. This deduction allows property owners to claim a portion of the property taxes paid on the secondary properties.Special Assessment Deduction
How Exemptions and Deductions are Applied, How to calculate property tax
Exemptions and deductions are applied to reduce the taxable value of the property, which in turn reduces the property taxes owed. For example, if the taxable value of a property is $100,000 and the homestead exemption reduces the taxable value by 10%, the taxable value would be $90,000.- Exemptions and deductions can save property owners money on their property taxes.
- Property owners can claim multiple exemptions and deductions, depending on their individual circumstances.
- The exemption or deduction amount is typically a percentage of the taxable value of the property.
Considering Special Assessments and Levies
Special assessments and levies are crucial components of property taxation that can significantly impact property owners. These assessments are used to fund specific improvements or services that benefit individual properties or a specific area within a jurisdiction. In this section, we will explore the types of special assessments and levies, how they are calculated, and the payment process.Types of Special Assessments
Special assessments are typically levied to fund specific improvements or services that benefit individual properties or a specific area within a jurisdiction. Some common types of special assessments include:- Assessments for Road Improvements Special assessments for road improvements are levied to fund the construction or improvement of roads that benefit specific properties. These assessments may include the cost of road paving, widening, or reconstruction.
- Assessments for Fire Protection Services Special assessments for fire protection services are levied to fund the installation or upgrading of fire hydrants, fire alarms, and other fire safety equipment.
- Assessments for Other Public Improvements Other types of special assessments may include funding for park improvements, sewer and water system upgrades, and other public improvements that benefit specific properties or areas.
Calculating Special Assessments
The amount of a special assessment is typically calculated based on the benefit each property receives from the improvement or service being funded. The assessment is usually expressed as a cost per unit of property value, such as per dollar of assessed value or per square foot of property area.Special assessments are usually calculated as a percentage of the assessed value of the property or as a fixed amount per unit of property area.For example, if a special assessment is levied to fund the construction of a new road that benefits a property with an assessed value of $100,000, and the assessment is calculated at 0.5% of the assessed value, the property owner would be responsible for paying $500 (0.5% x $100,000).
Paying Special Assessments
Property owners are usually required to pay special assessments as part of their annual property tax bill. The payment process may vary depending on the jurisdiction and the type of special assessment. Some common payment methods include:- Annual Payment Property owners may be required to pay special assessments in equal annual installments over a specified period, usually 5-10 years.
- One-Time Payment Some special assessments may require a one-time payment, which can be made at the time the assessment is levied.
- Mortgage Payments Special assessments may be added to the property owner's mortgage payments, depending on the agreement with the lender.
Organizing Property Tax Payments and Records
Organizing property tax payments and records is a crucial step in managing your property's financial and legal aspects. Keeping accurate records helps you stay informed about your property's tax obligations, avoid late fees, and ensure compliance with local regulations.When it comes to property tax payments and records, accuracy and organization are key. Inaccurate or incomplete records can lead to missed payments, fines, and penalties. On the other hand, organized records can help you identify areas of savings, optimize your tax strategy, and make informed decisions about your property.
Why Accurate Records are Essential
Accurate records of property tax payments and assessments are crucial for several reasons. Firstly, they help you stay on top of your tax obligations, ensuring you make timely payments and avoid late fees. Secondly, they provide a clear understanding of your property's tax burden, enabling you to identify areas of savings and optimize your tax strategy.Tips for Organizing Property Tax Payments and Records
To keep your property tax payments and records organized, consider the following tips:- Use a Spreadsheet: Consider using a spreadsheet like Google Sheets or Microsoft Excel to track your property tax payments and assessments. You can set up columns to record the date of payment, payment amount, and any relevant notes or receipts.
- Accounting Software: If you have a larger portfolio of properties or more complex tax obligations, consider using accounting software like QuickBooks or Xero. These tools can help you track expenses, manage cash flow, and generate reports for tax purposes.
- Retailer Receipts: Keep all receipts for property tax payments, assessments, and any other relevant expenses. You'll need these records to verify your payments and deductions.
- Organize Digital Copies: Scan your receipts and store them digitally in a secure cloud storage service like Dropbox or Google Drive. This way, you can access them from anywhere and ensure they're safely stored in case of physical loss or damage.
Tracking Property Tax Payments
Tracking property tax payments is a critical aspect of property tax management. Here are some ways to do it:- Calendar Reminders: Set reminders on your calendar to ensure you make timely payments. You can also use a separate calendar for property tax payments to keep them organized.
- Automated Payments: Consider setting up automated payments through your bank or accounting software. This way, you can ensure timely payments without having to manually initiate them each time.
- Payment History: Keep a record of all property tax payments, including the date, payment amount, and any relevant notes or receipts. This will help you track your progress and identify any issues or discrepancies.
Understanding Property Tax Liens and Foreclosure

Creation and Enforcement of Property Tax Liens
A property tax lien is created when a property owner fails to pay their property taxes on or before the deadline. The government will then send a notice to the property owner informing them of the lien and the amount owed. The lien will be recorded with the county recorder's office and will become a public record. The property owner will be responsible for paying the lien in full, plus interest and any additional fees.- Notification of Delinquency: The property owner will receive a notice from the government indicating that their property taxes are delinquent.
- Recording of Lien: The lien will be recorded with the county recorder's office, creating a public record.
- Payment of Lien: The property owner will be responsible for paying the lien in full, plus interest and any additional fees.
Tax Foreclosure: A Last Resort for Governments
If the property owner fails to pay the lien, the government may initiate a tax foreclosure action. This is a legal process that allows the government to sell the property to satisfy the outstanding tax debt. The property owner will typically be notified of the foreclosure action and will have the opportunity to redeem the property by paying the outstanding debt, plus interest and fees.- Notification of Foreclosure: The property owner will receive a notice from the government indicating that their property is being foreclosed upon.
- Negotiation of Redemption: The property owner will have the opportunity to negotiate with the government to redeem the property by paying the outstanding debt, plus interest and fees.
- Sale of Property: If the property owner fails to redeem the property, it will be sold at a public auction to satisfy the outstanding tax debt.
Impact on Property Owners: Consequences of Tax Foreclosure
Property owners who fail to pay their property taxes and are subject to tax foreclosure may face significant consequences, including:- Loss of Property: The property may be sold at a public auction to satisfy the outstanding tax debt.
- Damage to Credit Score: Foreclosure can significantly damage a property owner's credit score.
- Economic Impact: The loss of property can have a significant economic impact on the property owner and their family.
Calculating Property Tax Savings with Improvements
When you make improvements to your property, such as energy-efficient upgrades or additions, you may be able to reduce your property tax liability. In this section, we'll discuss the potential property tax savings that may result from these improvements and explain how to calculate the potential savings.Understanding the Impact of Improvements on Property Value
Improvements to your property can increase its value, which can lead to higher property taxes. However, the good news is that the increased value is not always reflected in the property tax assessment. The assessor may not account for the improvements when calculating the tax assessment, or they may apply a lower assessment ratio to the increased value. This means that you may be able to save on property taxes even if the improvements increase the property's value.Calculating Potential Property Tax Savings
To calculate the potential property tax savings associated with improvements, you'll need to determine the increased value of your property and apply the reduction in assessment ratio. Here's a step-by-step guide:* Determine the cost of the improvements made to your property. This includes the total cost of materials, labor, and any other expenses related to the project.
For example, let's say you made $10,000 in improvements to your property and estimated that the increase in value is $15,000. If the reduction in assessment ratio is 20%, the new assessment value would be $12,000 (70% of the increased value). Assuming a tax rate of 1.5%, the new property tax liability would be $180 (1.5% of $12,000).
Property tax savings = (Increased property value x Reduction in assessment ratio) - New assessment valueKeep in mind that the actual property tax savings will depend on various factors, including the type of improvement, the location, and the local tax laws and regulations. It's essential to consult with a tax professional to determine the potential property tax savings associated with your specific improvement.
Benefits of Energy-Efficient Improvements
Energy-efficient improvements, such as solar panels, energy-efficient windows, and insulation, can significantly increase your property's value and lead to potential property tax savings. In addition to tax benefits, these improvements can also reduce your energy costs and contribute to a more sustainable future.When considering energy-efficient improvements, it's essential to factor in the potential property tax savings in addition to the energy savings. This will help you make a more informed decision about the investments you make in your property.
Timing and Documentation
It's crucial to document the improvements made to your property and the estimated increase in value. This documentation will help you demonstrate the property's increased value to the assessor and support your claim for potential property tax savings. Additionally, make sure to notify the assessor of the improvements and submit any necessary paperwork to ensure that the increased value is reflected in the property tax assessment.Designing a Property Tax Budget and Plan
Creating a comprehensive property tax budget and plan is essential for homeowners and businesses to manage their property tax obligations effectively. A well-designed property tax budget and plan helps individuals and organizations anticipate and plan for upcoming property tax payments, avoiding late fees and penalties. It also enables them to make informed decisions about property improvements and investments, taking into account the potential impact on property tax liabilities.A property tax budget and plan should include the following key components:
Identifying Property Tax Obligations
To develop a comprehensive property tax budget and plan, it is crucial to identify all property tax obligations, including annual property tax payments, special assessments, and levies. This involves reviewing property tax bills, checking for any changes in property tax rates or exemptions, and considering any outstanding property tax liens.- Annual property tax payments: Calculate the annual property tax payment amount based on the property's assessed value and applicable tax rates.
- Special assessments and levies: Identify any special assessments or levies that may be imposed on the property, such as for infrastructure or school district improvements.
- Outstanding property tax liens: Check for any outstanding property tax liens that may have been levied against the property.
Estimating Property Value Adjustments
Property value adjustments can significantly impact property tax liabilities. It is essential to estimate any potential property value adjustments, such as increases due to renovations or decreases due to market downturns.- Review recent property sales: Research recent property sales in the area to determine the market value of the property.
- Assess property improvements: Evaluate any property improvements or renovations that may have increased the property's value.
- Consider market trends: Take into account any changes in market trends that may impact property values.
Calculating Projected Property Tax Savings
By accurately estimating property value adjustments, individuals and businesses can calculate projected property tax savings resulting from property improvements or other factors.- Determine the property tax savings: Calculate the projected property tax savings resulting from the property value adjustment.
- Review tax incentives: Evaluate any tax incentives or exemptions that may apply to the property.
- Consider long-term benefits: Consider the long-term benefits of property improvements, including increased property value and potential rental income.
Reviewing and Adjusting the Property Tax Budget
Regular review and adjustment of the property tax budget are essential to ensure compliance with property tax obligations and maximize property tax savings.- Review property tax bills: Regularly review property tax bills to ensure accuracy and identify any changes in property tax rates or exemptions.
- Update the property tax budget: Update the property tax budget to reflect any changes in property tax rates, exemptions, or property value adjustments.
- Adjust property tax payments: Adjust property tax payments accordingly to ensure compliance with property tax obligations.
Summary
In conclusion, calculating property tax is a critical step in understanding your property tax obligations and ensuring compliance with property tax laws. By following the steps Artikeld in this guide, property owners can determine their property tax obligations, identify exemptions and deductions, and make informed decisions about their property tax payments.
FAQ Section: How To Calculate Property Tax
Can I claim a homestead exemption if I rent my property?
No, a homestead exemption is typically only available to property owners who occupy their property as their primary residence. If you rent your property, you may not be eligible for a homestead exemption.
How often do I need to pay property taxes?
Property tax payments are usually due twice a year, in March and September. However, the frequency and due dates of property tax payments may vary depending on your local government and property tax laws.
Can I deduct property taxes from my income tax?
No, property taxes are not deductible from your income tax. However, you may be able to claim a tax credit for property taxes paid in certain circumstances.
What happens if I don't pay my property taxes?
If you don't pay your property taxes, your property may be subject to foreclosure, and you may face other legal consequences, such as fines and penalties.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of guessthescore.