How to Calculate Opportunity Cost for Effective Decision Making
Table of Contents
- Understanding Opportunity Cost as a Tool for Decision Making in Complex Economic Scenarios
- Key Differences from Sunk Cost
- Key Differences from Marginal Cost
- Example: A Business Decision Involving Resource Allocation
- Calculating Opportunity Cost Using Marginal Analysis and Incremental Costs
- Step-by-Step Procedure for Calculating Opportunity Cost
- Incorporating Time Preferences and Opportunity Cost in Decision-Making Processes
- Time Preferences and Opportunity Cost
- Opportunity Cost in Real-World Applications - Case Studies and Examples
- Investment Decisions
- Supply Chain Management
- Military Procurement
- Incorporating Intangible Factors into Opportunity Cost Calculations
- Quantifying Intangible Factors
- Benefits of Incorporating Intangible Factors
- Challenges of Incorporating Intangible Factors
- Limitations of Opportunity Cost in Economic Analysis
- Restrictive Assumptions
- Ignores Non-Monetary Costs, How to calculate opportunity cost
- Does Not Account for Externalities
- Ignores Time Preferences
- Requires Perfect Knowledge of the Future
- Conclusion: How To Calculate Opportunity Cost
- Helpful Answers
Delving into how to calculate opportunity cost, this introduction immerses readers in a unique and compelling narrative, making them realize the significance of opportunity cost in economic decision making processes. Opportunity cost, a fundamental concept in economics, refers to the value of the next best alternative foregone due to a particular decision or action.
Calculating opportunity cost involves evaluating the potential benefits and costs of a decision, weighing the trade-offs and outcomes to make informed choices. This process requires consideration of various factors, including marginal costs, incremental costs, and time preferences, to determine the optimal decision that maximizes value and minimizes losses.
Throughout this article, we will explore the steps and considerations involved in calculating opportunity cost, as well as real-world applications and examples to illustrate its importance and relevance.
Understanding Opportunity Cost as a Tool for Decision Making in Complex Economic Scenarios
Opportunity cost plays a vital role in evaluating trade-offs between competing alternatives, allowing individuals and businesses to make informed decisions in complex economic scenarios. It highlights the value of the next best alternative that is given up when resources, time, or efforts are allocated to a particular option. This concept differs from other economic concepts such as sunk cost and marginal cost in several ways.
Key Differences from Sunk Cost
Sunk cost refers to the resources that have already been invested or spent on a particular project or investment. These costs cannot be recovered and thus do not affect the decision-making process of future investments. Opportunity cost, on the other hand, focuses on the potential benefits that are given up when resources are allocated to a particular option. Unlike sunk cost, opportunity cost is relevant to future decision-making, as it takes into account the value of the next best alternative.
Key Differences from Marginal Cost
Marginal cost, also known as variable cost, is the additional cost of producing one more unit of a good or service. While marginal cost is concerned with the short-term costs incurred to produce an additional unit, opportunity cost is concerned with the long-term benefits given up due to resource allocation. These two concepts are closely related but distinct in their focus.
Example: A Business Decision Involving Resource Allocation
A company, Green Energy, is considering two alternatives to allocate its resources: investing in renewable energy sources or expanding its existing operations. The opportunity cost of investing in renewable energy sources is the potential revenue that could be earned by expanding its existing operations. On the other hand, the opportunity cost of expanding its existing operations is the potential revenue that could be earned by investing in renewable energy sources.
| Resource Allocation Option | Opportunity Cost |
| --- | --- |
| Investing in Renewable Energy Sources | Potential Revenue Earned by Expanding Existing Operations |
| Expanding Existing Operations | Potential Revenue Earned by Investing in Renewable Energy Sources |
In this scenario, the opportunity cost of investing in renewable energy sources is the potential revenue that could be earned by expanding its existing operations. By considering the opportunity cost, Green Energy can make an informed decision about which option to pursue, taking into account the potential benefits of each alternative.
Opportunity cost is the value of the next best alternative that is given up when resources are allocated to a particular option.Green Energy decides to invest in renewable energy sources due to the potential environmental benefits and long-term savings on energy costs. The opportunity cost of this decision is the potential revenue earned by expanding its existing operations, which is valued at $1 million. This decision allows Green Energy to minimize its environmental impact and maximize its long-term benefits.
In this example, Green Energy used opportunity cost to make a difficult financial decision involving resource allocation. By considering the potential benefits given up due to resource allocation, the company was able to make an informed decision that aligns with its long-term goals and values.
Calculating Opportunity Cost Using Marginal Analysis and Incremental Costs
Marginal analysis plays a crucial role in determining whether a decision is economically viable, as it involves evaluating the additional costs or benefits that arise from a specific action or investment. In the context of opportunity cost, marginal analysis helps businesses and individuals understand the trade-offs involved in making a decision. By calculating opportunity cost using incremental costs, individuals can make informed decisions about the most valuable use of resources. This is particularly useful in situations where resources are limited, and decision-makers must weigh the potential benefits of one option against the costs of another.Step-by-Step Procedure for Calculating Opportunity Cost
Calculating opportunity cost using marginal analysis involves identifying the incremental costs associated with a decision, which represent the additional resources required to achieve a specific outcome. Here's a step-by-step guide to calculating opportunity cost:- Determine the Marginal Benefit: The first step is to identify the marginal benefit, which represents the extra benefit or outcome that can be achieved by investing in a particular project or activity. This could be in the form of increased revenue, cost savings, or improved efficiency.
- Identify the Incremental Costs: The next step is to identify the incremental costs associated with the decision, which represent the additional resources required to achieve the marginal benefit. These costs could include the initial investment, labor costs, material costs, or other expenses.
- Determine the Opportunity Cost: The opportunity cost is the value of the next best alternative that is given up as a result of making a decision. This can be calculated by multiplying the incremental costs by the opportunity cost rate, which represents the rate at which the opportunity cost is generated.
- Calculate the Opportunity Cost: The opportunity cost is calculated by multiplying the incremental costs by the opportunity cost rate. This will give you the total opportunity cost associated with the decision.
- Example: A company is considering investing in a new marketing campaign to increase sales. The marginal benefit of the campaign is estimated to be $10,000 in additional revenue. However, the incremental costs associated with the campaign are estimated to be $8,000 in labor and material costs.
- Step-by-Step Calculation:
- The opportunity cost rate is 10% (assuming a 10% opportunity cost rate).
- The incremental costs are $8,000.
- The opportunity cost is calculated by multiplying the incremental costs by the opportunity cost rate: Opportunity Cost = $8,000 x 0.10 = $800.
- Example: A company is considering investing in a new marketing campaign to increase sales. The marginal benefit of the campaign is estimated to be $10,000 in additional revenue. However, the incremental costs associated with the campaign are estimated to be $8,000 in labor and material costs.
Incorporating Time Preferences and Opportunity Cost in Decision-Making Processes
Time Preferences and Opportunity Cost
In economic theory, individuals are assumed to have a time preference, which reflects their attitude towards time. This preference affects how they weigh the benefits of a decision today against the benefits of delaying a decision. Three common time preferences are immediate gratification, patience, and impulsiveness. Each of these preferences influences the way individuals calculate opportunity cost, leading to different decision-making outcomes.Immediate Gratification: Individuals with an immediate gratification time preference prioritize short-term benefits over long-term gains. This preference implies that they are less concerned with the future and more focused on current needs. As a result, their opportunity costs are often high, as they are willing to trade off long-term benefits for immediate rewards.
Patience: In contrast, individuals with a patient time preference prioritize long-term benefits over short-term gains. This preference suggests that they are more concerned with the future and are willing to delay gratification to achieve greater rewards in the long run. As a result, their opportunity costs are often low, as they are willing to invest in future benefits.
Impulsiveness: Individuals with an impulsive time preference exhibit a mix of present and future-oriented behavior. This preference implies that they are prone to making impulsive decisions based on short-term benefits, but also consider long-term consequences. As a result, their opportunity costs are often moderate, as they balance immediate and future rewards.
- Assume an individual with an immediate gratification time preference decides to spend $100 on a concert ticket instead of saving it for a long-term investment. In this scenario, the opportunity cost is the long-term benefits they would have gained from investing the money, such as interest rates or appreciation in value.
- Consider an individual with a patient time preference who decides to delay a purchase to save for a bigger reward in the future. The opportunity cost in this scenario is the immediate gratification they would have gained from purchasing the item now, versus the long-term benefits they will achieve by delaying the purchase.
- A person with an impulsive time preference decides to spend money on a spontaneous vacation, but also considers the long-term impact on their finances. The opportunity cost in this scenario is the trade-off between the immediate gratification of the vacation and the potential long-term costs of overspending or impacting their financial stability.
Time preference affects the opportunity cost of a decision, as it influences how individuals weigh the benefits of a decision today against the benefits of delaying a decision. Understanding time preferences is crucial for making informed decisions that balance short-term and long-term benefits.
Opportunity Cost in Real-World Applications - Case Studies and Examples
Opportunity cost is a crucial concept in economics that helps individuals and organizations make informed decisions by evaluating the trade-offs involved in their choices. In this section, we will explore various real-world applications of opportunity cost and analyze how it can be used effectively in decision-making processes.Investment Decisions
Investment decisions often involve weighing the potential returns against the potential losses, which is where opportunity cost comes into play. Consider the case of Apple Inc. and its decision to invest in the development of the iPhone.Image: Apple Inc.'s iPhones have revolutionized the mobile phone industry, making it one of the most successful product lines in the company's history. However, this success came at a significant opportunity cost, as Apple had to divert resources away from other product lines and research and development projects.
In 2007, Apple faced a critical crossroads in its history. The company had to decide whether to invest in the development of a new mobile phone that would potentially revolutionize the industry. The opportunity cost of this investment was significant, as Apple had to divert resources away from other product lines and research and development projects.
Apple decided to invest in the iPhone, and the results were phenomenal. The iPhone became one of the most successful product lines in Apple's history, generating billions of dollars in revenue and cementing the company's position as a leader in the technology industry.
Pros:
Cons:
Supply Chain Management
Opportunity cost can also be applied to supply chain management, where companies have to weigh the costs of different production options. Consider the case of Walmart and its decision to establish a robust supply chain management system.Image: Walmart's supply chain management system has been a key factor in its success, allowing the company to maintain low prices and deliver products to customers quickly. However, this system requires significant investment and resources, which comes with an opportunity cost.
Walmart faced a critical decision in the 1990s about how to manage its supply chain. The company had to weigh the opportunity costs of investing in a robust supply chain management system versus relying on its existing distributors and suppliers.
Walmart decided to invest in a robust supply chain management system, which allowed the company to maintain low prices and deliver products to customers quickly. This decision came with significant opportunity costs, as Walmart had to divert resources away from other areas of the business.
Pros:
Cons:
Military Procurement
Opportunity cost can also be applied to military procurement, where governments have to weigh the costs of different production and procurement options. Consider the case of the US Department of Defense and its decision to procure the F-35 fighter jet.Image: The F-35 fighter jet has been one of the most expensive military procurement projects in history, with the US Department of Defense facing significant opportunity costs as it diverted resources away from other areas of the military budget.
The US Department of Defense faced a critical decision about which fighter jet to procure as a replacement for the US Air Force's aging F-16 fleet. The opportunity cost of procuring the F-35 was significant, as it meant diverting resources away from other areas of the military budget.
Despite the high costs, the US Department of Defense decided to procure the F-35, citing its advanced capabilities and potential for future upgrades.
Pros:
Cons:
Incorporating Intangible Factors into Opportunity Cost Calculations
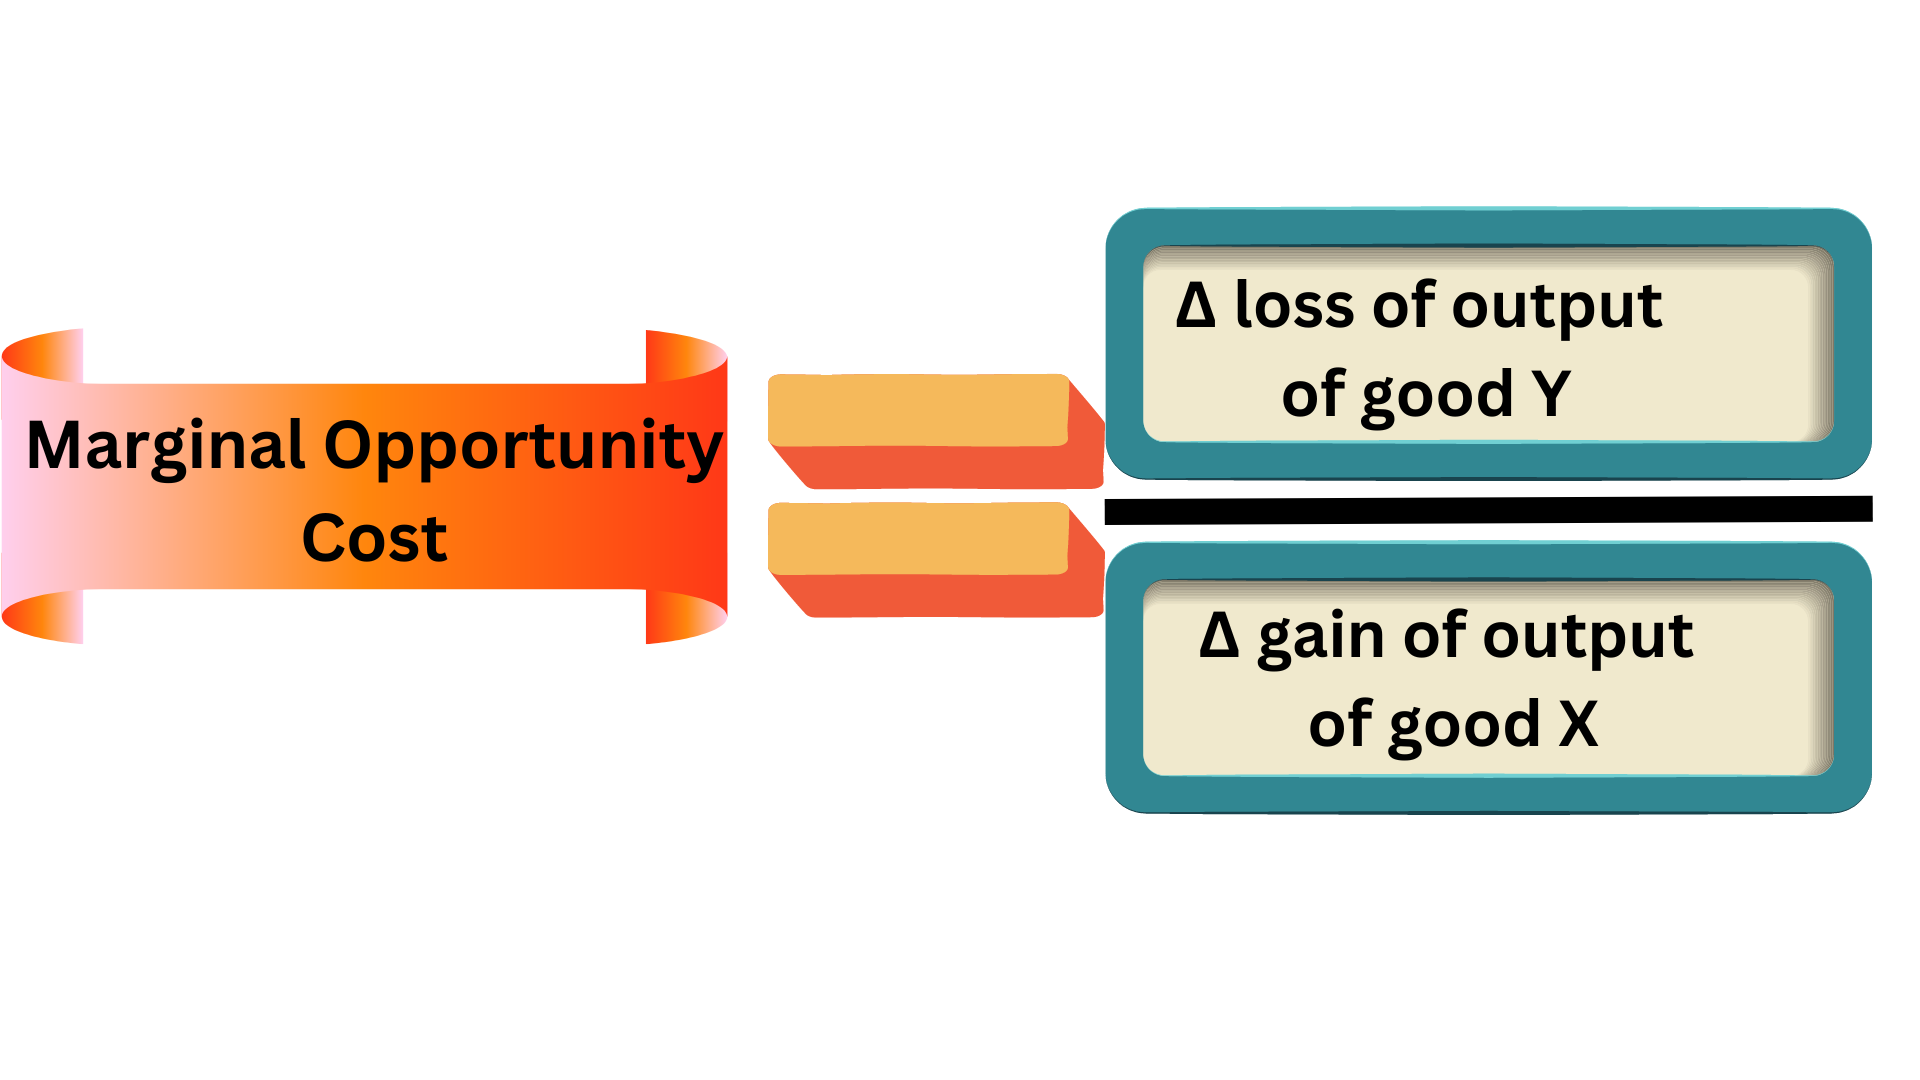
Quantifying Intangible Factors
Intangible factors can be quantified using various methods, including cost-benefit analysis, stakeholder analysis, and scenario planning. For instance, brand equity can be calculated by assessing the value of a company's brand, including its reputation, customer loyalty, and market share. Employee satisfaction can be measured using surveys, focus groups, and other tools to assess employee engagement, morale, and productivity. Social responsibility can be quantified through environmental and social impact assessments, which evaluate a company's contribution to sustainability, equality, and human rights.Benefits of Incorporating Intangible Factors
Incorporating intangible factors into opportunity cost calculations offers several benefits, including:- Improved Decision-Making: By considering intangible factors, businesses can make more informed decisions that take into account the long-term consequences of their actions.
- Increased Stakeholder Satisfaction: By prioritizing intangible factors, companies can demonstrate their commitment to stakeholder well-being, leading to increased loyalty and retention.
- Better Risk Management: Incorporating intangible factors can help businesses identify potential risks and opportunities, enabling them to develop effective risk management strategies.
- Enhanced Reputation: By prioritizing intangible factors, companies can enhance their reputation, leading to increased brand value and competitiveness.
Challenges of Incorporating Intangible Factors
Despite the benefits, incorporating intangible factors into opportunity cost calculations can be challenging, including:- Difficulty in Quantification: Intangible factors can be difficult to quantify, making it challenging to assign a numeric value to them.
- Lack of Data: Limited data on intangible factors can make it difficult to develop accurate estimates.
- Subjectivity: Intangible factors can be subjective, making it challenging to agree on a universally acceptable value.
- Resource Intensive: Incorporating intangible factors into opportunity cost calculations can be resource-intensive, requiring significant time and effort.
Limitations of Opportunity Cost in Economic Analysis
Opportunity cost is a fundamental concept in economics that helps decision-makers evaluate the trade-offs between different choices. However, like any other analytical tool, opportunity cost has its limitations. In this section, we will discuss some of the limitations of opportunity cost in economic analysis.Restrictive Assumptions
Opportunity cost analysis relies on a set of restrictive assumptions, such as:- Perfect competition: Opportunity cost assumes that markets are perfectly competitive, with many firms producing a homogeneous product and free entry and exit. In reality, markets are often imperfectly competitive, with few firms dominating the market and barriers to entry.
- Full information: Opportunity cost assumes that decision-makers have perfect information about the costs and benefits of different choices. In reality, decision-makers often face uncertainty and incomplete information.
- Rational behavior: Opportunity cost assumes that decision-makers behave rationally and make choices that maximize their welfare. In reality, decision-makers may behave irrationally or engage in self-interested behavior.
Ignores Non-Monetary Costs, How to calculate opportunity cost
Opportunity cost only considers monetary costs, ignoring non-monetary costs that can be significant in many economic decisions. For example, a decision to invest in a new project may have environmental or social costs that are not captured by opportunity cost analysis.Does Not Account for Externalities
Opportunity cost analysis ignores externalities, which are costs or benefits that are not reflected in market prices. For example, a decision to invest in a new factory may have negative externalities, such as pollution, that are not captured by opportunity cost analysis.Ignores Time Preferences
Opportunity cost analysis assumes that decision-makers have the same time preferences for different choices. In reality, decision-makers may have different time preferences, such as a preference for immediate gratification or a willingness to wait for future benefits.Requires Perfect Knowledge of the Future
Opportunity cost analysis requires decision-makers to have perfect knowledge of the future, including the cost and benefit of different choices. In reality, decision-makers often face uncertainty and incomplete information about the future, making it difficult to accurately estimate opportunity costs.Opportunity cost analysis is a useful tool for decision-making, but it has several limitations that must be considered when applying it in real-world scenarios.
Conclusion: How To Calculate Opportunity Cost
In conclusion, calculating opportunity cost is a crucial aspect of decision making in economics, business, and personal finance. By understanding and evaluating opportunity cost, individuals and organizations can make more informed choices, avoid costly mistakes, and achieve their goals more effectively. Remember, every decision has a cost, but with the right tools and knowledge, you can make the most of your resources and maximize your opportunities.
Helpful Answers
What is opportunity cost, and why is it important?
Opportunity cost is the value of the next best alternative foregone due to a particular decision or action. It is essential to calculate opportunity cost to evaluate the trade-offs and outcomes of a decision, ensuring that you make the most of your resources and maximize your opportunities.
How do I calculate opportunity cost?
To calculate opportunity cost, you need to evaluate the potential benefits and costs of a decision, weighing the trade-offs and outcomes to make an informed choice. This involves considering factors like marginal costs, incremental costs, and time preferences.
Can you give an example of calculating opportunity cost in real life?
Suppose a company needs to decide whether to invest in a new project or maintain its existing operations. The opportunity cost of investing in the new project would be the potential revenue foregone from maintaining its existing operations. By evaluating the opportunity cost, the company can make an informed decision that maximizes its value.
How does time preference influence opportunity cost?
Time preference affects opportunity cost by altering the perceived value of future outcomes. For example, if someone has a high time preference, they may prioritize short-term gains over long-term benefits, leading to different opportunity cost calculations.
Can you provide a simple example of how to incorporate intangible factors into opportunity cost calculations?
Suppose a company is evaluating the opportunity cost of investing in employee training. In addition to financial costs, the company should consider intangible factors like employee satisfaction and brand equity to calculate a more comprehensive opportunity cost.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of guessthescore.