How to File Chapter 13 with No Money
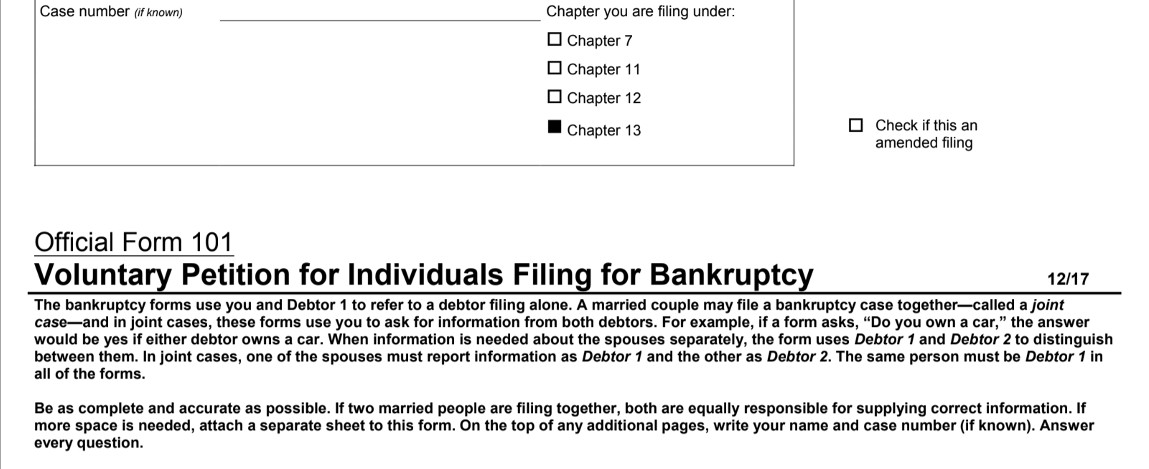
Table of Contents
- Understanding Chapter 13 Bankruptcy and Its Purpose
- Types of Debts That Can Be Discharged Through Chapter 13 Bankruptcy
- Comparison of Advantages of Chapter 13 Over Other Forms of Bankruptcy Protection
- Examples of Successful Chapter 13 Bankruptcy Cases
- Avoiding Common Mistakes When Filing for Chapter 13 Bankruptcy, How to file chapter 13 with no money
- Conclusion
- Assessing Eligibility for Chapter 13 Bankruptcy without Financial Means
- Criteria for Determining Eligibility
- Credit Counseling Requirements
- Necessary Documentation for Insolvency or Financial Hardship
- Preparing and Filing Chapter 13 Petition without Monetary Means
- Gathering Essential Financial Information and Documents
- The Role of Pro Bono Legal Services
- Impact on Credit Scores and Future Financial Opportunities
- Navigating Court Filings and Hearings with No Financial Resources: How To File Chapter 13 With No Money
- Potential Challenges of Navigating the Bankruptcy Court System
- The Importance of Retaining a Qualified and Affordable Bankruptcy Attorney
- Table of Necessary Paperwork and Court Documents
- Closure
- Q&A
As how to file chapter 13 with no money takes center stage, this opening passage beckons readers into a world crafted with good knowledge, ensuring a reading experience that is both absorbing and distinctly original.
Chapter 13 bankruptcy is a debt consolidation and repayment plan that can help individuals with no financial resources to reorganize their finances and get back on track.
Understanding Chapter 13 Bankruptcy and Its Purpose
Chapter 13 bankruptcy is a type of bankruptcy protection that allows individuals with a steady income to create a plan to repay a portion or all of their debts over time. This form of bankruptcy is often referred to as a wage earner's plan, as it is designed for individuals who can afford to make regular payments towards their debts.
This type of bankruptcy is particularly useful for individuals who are facing financial difficulties due to unforeseen circumstances such as job loss, medical emergencies, or divorce. By filing for Chapter 13 bankruptcy, individuals can gain breathing room to get back on their feet and create a plan to pay off their debts in a manageable and realistic manner.
Chapter 13 bankruptcy provides several advantages over other forms of bankruptcy protection. For instance, it allows individuals to keep their assets, such as their home or car, while still making payments towards their debts. Additionally, Chapter 13 bankruptcy can help individuals to discharge certain debts, such as credit card balances or personal loans, while still making payments on other debts, such as mortgages or car loans.
Types of Debts That Can Be Discharged Through Chapter 13 Bankruptcy
Through Chapter 13 bankruptcy, individuals can discharge various types of debts, including credit card balances, personal loans, medical bills, and past-due utility bills. These debts can be discharged over time, as Artikeld in the individual's Chapter 13 repayment plan.Debts that may not be eligible for discharge through Chapter 13 bankruptcy include:
- Certain taxes, such as federal or state taxes owed
- Income taxes owed to a foreign government
- Most student loans
- Fines or penalties imposed by a government agency
- Delinquent child support or alimony payments
Comparison of Advantages of Chapter 13 Over Other Forms of Bankruptcy Protection
Chapter 13 bankruptcy offers several advantages over other forms of bankruptcy protection, such as Chapter 7 bankruptcy. For instance:* Chapter 13 allows individuals to keep their assets, such as their home or car, while still making payments towards their debts.
By understanding the fundamental concepts of Chapter 13 bankruptcy and its purposes, individuals facing financial difficulties can make informed decisions about how to proceed with their debt management. With the right guidance and support, individuals can use Chapter 13 bankruptcy to get back on their feet and create a plan to pay off their debts in a manageable and realistic manner.
Examples of Successful Chapter 13 Bankruptcy Cases
Examples of successful Chapter 13 bankruptcy cases include:- An individual who has multiple credit card balances and is struggling to make payments, may use Chapter 13 bankruptcy to create a plan to pay off their credit card debt in equal installments over time, while still making mortgage payments.
- A homeowner who has fallen behind on their mortgage payments may use Chapter 13 bankruptcy to stop the foreclosure process and create a plan to catch up on their mortgage payments.
Avoiding Common Mistakes When Filing for Chapter 13 Bankruptcy, How to file chapter 13 with no money
Individuals who have decided to file for Chapter 13 bankruptcy should take the following precautions to avoid common mistakes:- Seek the guidance of a qualified bankruptcy attorney, as they can provide valuable advice on how to navigate the bankruptcy process.
- Maintain accurate records of all financial transactions, as they will be required during the bankruptcy process.
- Create a realistic Chapter 13 repayment plan, taking into account income, expenses, and debt obligations.
Conclusion
In conclusion, Chapter 13 bankruptcy provides a valuable option for individuals facing financial difficulties, allowing them to create a plan to pay off their debts in a manageable and realistic manner. With the right guidance and support, individuals can successfully navigate the Chapter 13 bankruptcy process and emerge financially stronger.Assessing Eligibility for Chapter 13 Bankruptcy without Financial Means
Assessing eligibility for Chapter 13 bankruptcy without financial means requires careful consideration of various factors. While income is typically a primary consideration, there are other criteria that can influence eligibility. This discussion focuses on factors unrelated to income, which can contribute to a decision on whether Chapter 13 bankruptcy is an appropriate option without relying solely on financial means.Criteria for Determining Eligibility
Several factors unrelated to income can impact eligibility for Chapter 13 bankruptcy. These include the type of debt, the amount of secured debt, and the presence of non-dischargeable obligations. Understanding these factors is essential in determining whether Chapter 13 bankruptcy is a viable option without financial means.- The type of debt is a crucial factor in determining eligibility for Chapter 13 bankruptcy. Typically, Chapter 13 is suitable for individuals with unsecured debts totaling less than $2,750,000, or with secured debts totaling less than $1,263,650. However, there are specific exceptions for certain types of debts, such as student loans, taxes, and child support.
- The amount of secured debt is also an essential consideration in determining eligibility for Chapter 13 bankruptcy. Secured debts include mortgage or vehicle loans, which may require special treatment, especially if the value of the secured asset is significantly lower than the debt.
- The presence of non-dischargeable obligations, such as taxes or child support, can prevent individuals from qualifying for Chapter 13 bankruptcy. Non-dischargeable debts are those that cannot be eliminated through bankruptcy and must be repaid in full.
Credit Counseling Requirements
Meeting specific credit counseling requirements is critical for Chapter 13 bankruptcy eligibility. Credit counseling is designed to help individuals understand the implications of bankruptcy and explore alternative options for managing debt.- The Credit Counseling requirement mandates a session with a qualified credit counselor, either in-person or over the phone. The credit counselor will discuss debt management alternatives, credit card debt, and a budget to meet financial obligations.
- Additionally, the National Foundation for Credit Counseling (NFCC) is an approved credit counseling agency for bankruptcy purposes. Their financial experts will review and assess the current financial situation, creating a tailored plan for debt repayment.
Necessary Documentation for Insolvency or Financial Hardship
Gathering necessary documentation for insolvency or financial hardship is essential for demonstrating the need for Chapter 13 bankruptcy. This documentation will typically include:- Financial statements, including income, expenses, assets, and liabilities.
- A list of all debts, including secured and unsecured creditors.
- A detailed account of income, including employment records, benefits, and any other sources of revenue.
- A plan for debt repayment, which must demonstrate the ability to repay a significant portion of debts over time.
Preparing and Filing Chapter 13 Petition without Monetary Means

To begin the process, it's essential to gather all the necessary financial information and documents. This may include:
Gathering Essential Financial Information and Documents
Gathering all necessary financial information and documents is a crucial step in the Chapter 13 bankruptcy process, regardless of whether you have monetary means. This includes:- Income statements and proof of employment
- Expense records, including rent/mortgage and utility bills
- A list of debts, including credit card balances and loan details
- Asset valuations and records of property ownership
- Identification documents, including a driver's license and social security card
The Role of Pro Bono Legal Services
Pro bono legal services can play a significant role in assisting individuals who are unable to pay the filing fee for a Chapter 13 petition. Pro bono lawyers are committed to providing free or reduced-cost legal services to those in need, and may be able to help individuals with the bankruptcy filing process. Some potential sources of pro bono legal services include:- Local legal aid organizations
- Non-profit law firms
- Bar associations
- Law schools and clinics
Finally, it's essential to understand the potential impact of filing a Chapter 13 petition on credit scores and future financial opportunities.
Impact on Credit Scores and Future Financial Opportunities
Filing a Chapter 13 petition can have a significant impact on credit scores and future financial opportunities. The bankruptcy process can remain on credit reports for up to 10 years from the date of filing, which may make it more difficult to obtain credit or loans in the future. However, it's also worth noting that Chapter 13 bankruptcy can provide an opportunity to reorganize and repay debts over time, which may ultimately lead to improved credit scores and greater financial stability.* Income-Based Payments: Allow debtors to allocate a percentage of their income towards debt repayment, ensuring that payments remain manageable despite fluctuating income.
* Credit Counseling: Work with a credit counselor to develop a repayment plan that meets the debtor's financial needs and takes into account creditor requirements.
* Essential Debts: Identify debts that are essential to maintaining a basic standard of living, such as rent/mortgage, utilities, and food expenses.
By implementing these strategies, debtors with minimal income can create a feasible repayment plan under Chapter 13 bankruptcy, maximizing their chances of successful debt repayment and financial recovery.
* Credit card balance: $5,000 @ 18% interest
To develop a repayment plan, the debtor would allocate a percentage of their income towards debt repayment, considering the essential debts and high-interest credit card balance. For instance:
50% of income: Essential debts (rent/mortgage, utilities, food expenses)By allocating a significant portion of income towards high-interest debt, the debtor can eliminate this debt within a reasonable timeframe, improving their overall financial situation.
Debtors should consult with a credit counselor or bankruptcy attorney to develop a personalized repayment plan that meets their unique financial circumstances. With careful planning and negotiation, debtors with minimal income can successfully repay their debts and emerge from Chapter 13 bankruptcy with a stronger financial foundation.
Navigating Court Filings and Hearings with No Financial Resources: How To File Chapter 13 With No Money
Navigating the bankruptcy court system can be a complex and daunting task, especially for those with limited financial resources. It requires a deep understanding of the legal process and a significant amount of paperwork. Without the financial means to hire an attorney or cover court fees, it may seem like an insurmountable obstacle. However, with the right guidance and preparation, individuals can successfully navigate the court system and achieve their financial goals.Potential Challenges of Navigating the Bankruptcy Court System
The potential challenges of navigating the bankruptcy court system with no financial resources are significant. These include:- Difficulty in completing paperwork and forms accurately and efficiently
- Lack of knowledge about the bankruptcy process and court procedures
- Inability to afford court fees and attorney representation
- Difficulty in communicating effectively with the court and creditors
The Importance of Retaining a Qualified and Affordable Bankruptcy Attorney
One of the most critical steps in navigating the bankruptcy court system with no financial resources is to retain a qualified and affordable bankruptcy attorney. A skilled attorney can provide invaluable guidance and support throughout the process, helping to ensure that all necessary paperwork is completed accurately and efficiently. They can also help individuals understand the complex legal process and make informed decisions about their financial future.A qualified bankruptcy attorney can make all the difference in navigating the court system.
Table of Necessary Paperwork and Court Documents
| Document Name | Description | Filing Requirements |
| Voluntary Petition | Formal request to initiate bankruptcy | Name, address, contact information |
| Means Test Calculation | Document detailing income and expenses | Required income verification and expense documentation |
| Chapter 13 Plan | Repayment plan for creditors | Proof of debt and plan details |
Closure
In conclusion, filing chapter 13 with no money requires careful preparation, a good understanding of the bankruptcy process, and the help of a qualified and affordable bankruptcy attorney.
By following the steps Artikeld in this article, individuals can navigate the complex process of chapter 13 bankruptcy and emerge with a clear plan for financial recovery and a fresh start.
Q&A
What is Chapter 13 bankruptcy, and how does it differ from Chapter 7?
Chapter 13 bankruptcy is a debt consolidation and repayment plan that lasts for 3-5 years, whereas Chapter 7 is a liquidation bankruptcy that eliminates most debts in a matter of months.
Can I file for Chapter 13 bankruptcy with no income?
Yes, you can file for Chapter 13 bankruptcy with no income, but you'll need to demonstrate insolvency or financial hardship to meet the eligibility criteria.
Will filing for Chapter 13 bankruptcy ruin my credit score?
Filing for Chapter 13 bankruptcy will likely damage your credit score, but it will also stop creditors from pursuing you for payments, and you'll have a chance to reorganize your finances and improve your credit score over time.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of guessthescore.